

How VALID
InstantFUNDS Works
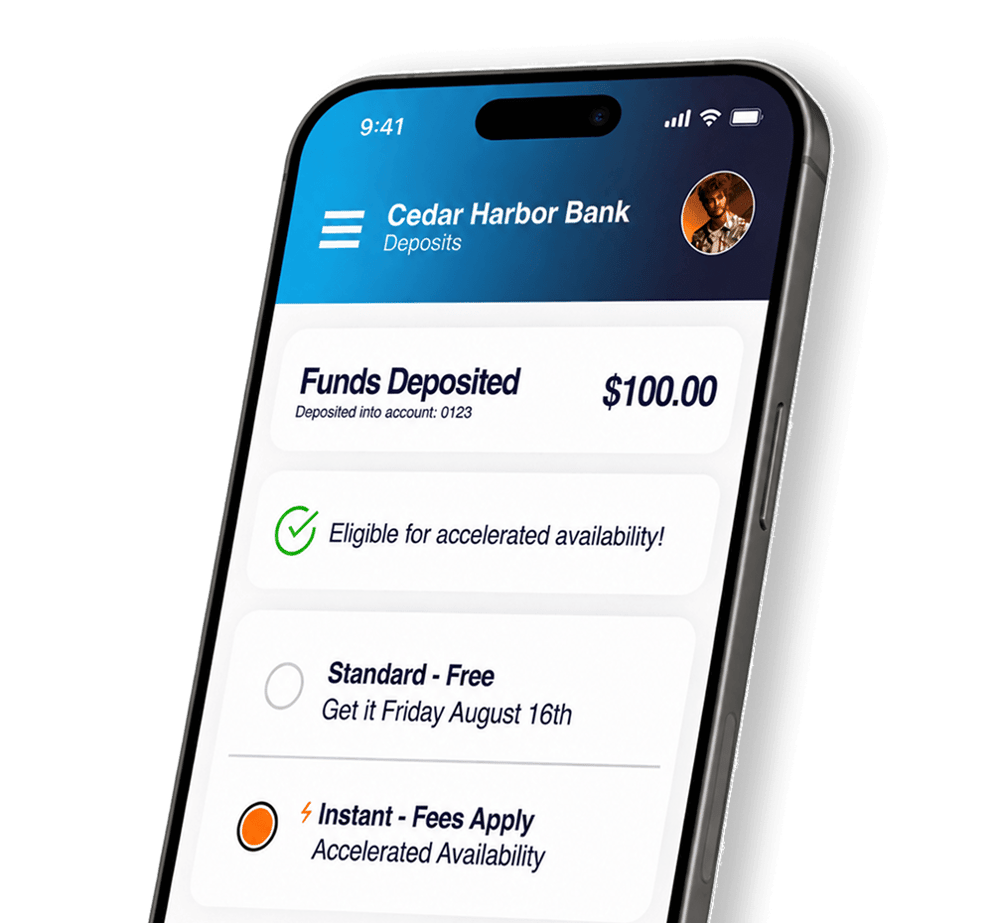
For an eligible deposit, the interface displays the fee set by the institution before the customer makes a choice.
The customer sees the terms.
The customer can accept the offer for accelerated funds or continue with the institution’s standard availability.
The customer chooses.
When the customer accepts, eligible funds are made available on the accelerated timeline.
Funds are made available.
A deposit model built around aligned incentives
Reduce fraud and customer friction
Most fraud solutions introduce friction to both the institution and their customers. With InstantFUNDS, VALID owns the exposure while removing unnecessary holds.
InstantFUNDS
When customers choose speed, everyone shares in the value.
InstantFUNDS gives eligible customers the choice of immediate access to deposited funds for an institution-set fee. You share in the revenue; VALID absorbs the return risk if an approved deposit is later returned for any reason.
No surprise fees.
No hidden tradeoff.
Customers choose whether immediate access is worth the fee. Your institution sets the percentage, and the exact amount is shown before they accept.
Visible before acceptance, so the customer knows the cost before making the decision.
Customer-elected, so faster access remains optional rather than automatic.
No statement surprise, because the charge is not introduced after the deposit is complete.
Institution-controlled, so each bank or credit union determines its own pricing approach.
Faster access keeps customers from leaving
Customers who switch primary checking accounts cite slow access to their funds as the #1 driver. InstantFUNDS gives them a reason to stay.
%
would have stayed if their needs were better met
%
less attrition after one InstantFUNDS use
%
less attrition after five or more uses
%
increase in mobile deposit usage
$ Billion
in deposits guaranteed monthly
A practical path from decision to launch
VALID works with each institution to connect the necessary deposit data, define eligibility and customer experience rules, configure pricing, test the decision flow, and prepare the offer for launch.
FAQ
Who sets the fee?
Each participating bank or credit union sets its own fee.
Who covers the check if it is returned?
VALID absorbs all approved and eligible returns; not the client or the institution.
What does the customer see?
For an eligible deposit, the customer receives an InstantFUNDS offer and can choose an option based on when they need access to their funds. The customer can choose immediate access or continue with standard availability.
What happens when a deposit is not eligible?
The customer simply receives standard funds availability.
Does every customer have to use InstantFUNDS?
No. It is an optional offer. Even when the offer appears, the customer can decline it.
How long does implementation take?
An implementation can take as little as 4 - 6 months, depending on the institution.
See how InstantFUNDS fits your strategy
Explore eligibility, pricing, customer experience, and fraud coverage for your institution.