
Industry
Financial Services
Challenge
The Bank processes over 2 million mobile and ATM check deposits per month. Customers expected immediate access to their funds, but the Bank had no real-time way to tell which checks were safe to release, and its self-service channels returned checks at about twice the rate of teller deposits.
Results
Following InstantFUNDS deployment on its mobile and ATM channels, passed deposits had about 97% lower losses per deposit and a return rate of about 0.2%, and about 80% (mobile) and 70% (ATM) of customers accepting InstantFUNDS were repeat users.
Key Product
InstantFUNDS
With no real-time risk decision, the Bank had no way to tell good deposits from risky ones at the moment of deposit. This created three compounding problems:
- Rising Customer Expectations - In a 2026 American Banker survey of 1,000 consumers who recently switched banks, conducted with VALID Systems, faster access to money was the most common primary reason for leaving their previous bank.
- Riskiest Channels - Mobile and ATM deposits made up 20% of the Bank’s check deposits but accounted for 34% of its returned items.
- No Real-Time Decision - Deposits ran through a bank-file process with no item-level risk score at the moment of deposit. Before InstantFUNDS, mobile and ATM checks were returned at 0.58% and 0.76%, about twice the rate of teller (0.33%) and other remote deposits (0.32%).
The InstantFUNDS Solution
InstantFUNDS scores each deposit in real time and returns one of three decisions: Passed, Failed, or Ineligible. The Bank can then offer immediate access on deposits that pass and focus review on the rest. Today, InstantFUNDS scores about 92% of the Bank’s mobile deposits and 58% of its ATM deposits.
Losses and Returns: Before InstantFUNDS vs. Passed Deposit
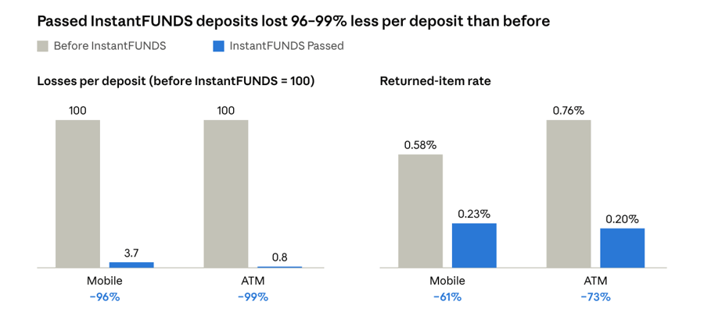
In real time, InstantFUNDS identified more than 80% of scored deposits as low-risk, enabling the Bank to make informed decisions about releasing funds to good customers. The charts below compare those deposits with each channel's results before InstantFUNDS.
Loss per deposit is shown as an index, with each channel’s before InstantFUNDS level set to 100.
 Returned-Item Rate by InstantFUNDS Decision
Deposits that passed InstantFUNDS were returned at about 0.2%, compared with 0.58% (mobile) and 0.76% (ATM) before InstantFUNDS.
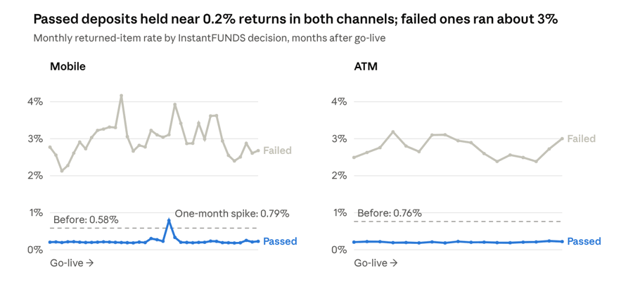
When a one-month surge in problem mobile deposits pushed returns on passed deposits to about 0.8%, InstantFUNDS adjusted quickly, flagging more of those deposits the next month. Within two months, returns were back to about 0.2%.
InstantFUNDS also pinpoints where the risk is: the 14% of scored mobile deposits it did not pass accounted for 70% of returned items among scored mobile deposits. That lets the Bank focus its review while still catching most problem items.
Customer Adoption
Customers also took up the option when InstantFUNDS was offered:
-
Offer acceptance: about 10% of InstantFUNDS offers on mobile deposits and 13% on ATM deposits were accepted.
-
Repeat use: in recent months, about 80% of mobile and 70% of ATM customers accepting the InstantFUNDS offer had used it before.
The Results
- From High Losses to Low Losses: Passed deposits had 96% (mobile) and 99% (ATM) lower losses per deposit than before InstantFUNDS.
- From Frequent to Rare Returns: Passed deposits were returned at about 0.2%, vs. 0.58% (mobile) and 0.76% (ATM) before InstantFUNDS.
- From Holds to Immediate Access: More than 80% of scored deposits were rated low-risk and eligible for immediate access.
- From One-Time to Repeat Use: About 80% of mobile and 70% of ATM customers accepting InstantFUNDS had used it before.
Why InstantFUNDS
For banks seeking to make confident, real-time funds-availability decisions for self-service deposits, the Bank’s results demonstrate four key benefits.
• Give customers what they want. Customers who use InstantFUNDS keep coming back.
• Release funds with confidence. InstantFUNDS separates low-risk deposits from risky ones, so most funds can be released immediately at a fraction of the losses.
• Focus review where risk is. The small share of deposits InstantFUNDS did not pass carried most of the risk, so teams can target their reviews.
• New service revenue. InstantFUNDS is an opt-in, paid service (typically 1–2% of the check amount); customers at the Bank accepted millions of offers.
About InstantFUNDS
InstantFUNDS is an opt-in service that lets customers access deposited check funds immediately instead of waiting for standard holds, typically for a small convenience charge of about 1–2% of the check amount. Banks offer it under their own brand names across mobile, ATM, and branch channels, all powered by VALID Systems’ real-time risk decisioning, which evaluates each check in seconds.
To see how InstantFUNDS could perform on your own deposit data, contact us to discuss a review.